The Pillars: Turning Side-Hustle Money Into a Gen X Retirement Plan
Almost no investing advice is written for a 50 year old funding a retirement account with $0.70 surveys and $10 website tests. Here is how I use small payouts to fund a Gen X retirement plan.
(Standard disclaimer: I am not a financial advisor, I am not picking stocks or funds for you to buy, and nothing on this site is formal investing advice. This is simply the plain-English blueprint of how I take small payouts from online side hustles and turn them into a real 15-year retirement structure.)
And the other half is doing.
And when you are 50 years old, have a mortgage, two teenagers, and a 10-to-15-year runway to retirement, knowing and doing are both pretty important.
When I wake up in the morning, like most people I open my phone. I check the news and whatever else that feels of importance. I groan about my age-related aches and pains and then grab my laptop to see what's out there to work on. A typical morning involves opening Prolific, Connect, Clickworker, and UserTesting. Usually it's a $0.70 survey, maybe a $2.00 AI voice review, and on occasion my personal favorite the $10.00 UserTesting audio-recorded website review (they don't mind my pre-coffee voice).
And why do I go through this exercise? Because I want to retire eventually. And almost all the investing advice on the internet: it wasn't written for us. Very few people are talking about the mechanics of building a brand new retirement pillar at age 50 when your regular paycheck is already spoken for – and your fresh capital is arriving in random $8.40 and $14.20 PayPal transfers twice a week.
In my earlier posts, I talked about waking up from the autopilot years (Paging My Inner Gekko), getting humbled when I realized "intuition and vibes" aren't an investment strategy (Warren Butthead), and learning the hard way why account types matter (The Math Started Mathing).
Now that the dust has settled and the structure is locked in – I'm not tinkering or chasing shiny objects anymore – I'm just feeding the machine.
Step 1: The Firewall ("No Lazy Money")
If you make $6.50 on Prolific and transfer it into the same checking account that pays for groceries, gas, or Quickie Mart runs, that $6.50 ceases to exist. It evaporates into the household budget and ten years from now you will have nothing to show for the twenty minutes you spent answering survey questions.
The entire engine behind Never2Late2Hustle is built on a single non-negotiable rule I laid out in All That's Silver is Gold Too: No Lazy Money.
Every single dollar that clears from the four(ish) platforms bypasses my household spending completely:
- Platforms pay out to PayPal (or direct deposit).
- Payouts get moved directly into my investment accounts.
- Every dollar is immediately given a job inside an asset that either grows over time, pays me a dividend to hold it, or protects the pile when the market gets ugly.
When you treat side-hustle money as "untouchable principal", those $.70 and $2 tasks stop feeling like pocket change. Across my Q3 Summer Results, those small payouts stacked up to $2,340+ in three months. That is real fuel.
Step 2: Why This Works Today
Twenty years ago, when we were in our twenties and thirties, you couldn't really invest "small" money efficiently. Every trade cost a $7.95 to $19.99 in broker commission and you had to buy whole shares. If a good broad-market fund cost $400 a share and you only had $15 from a side hustle, your money had to sit in cash collecting dust for months until you saved up enough for a single share.
Today, we actually do have the technology. Three modern features make "micro-investing" possible:
- Zero-Commission Trades: Buying $5.00 of an ETF costs $0 in transaction fees.
- Fractional Shares: You don't need $500 to buy a share of an S&P 500 or dividend-growth ETF. If you transfer $10.00 in from PayPal on a Thursday afternoon, you can buy 0.02 shares of a fund five minutes later. As I joked in my summer recap, my entire portfolio is literally being built fifty cents at a time.
- Automated DRIP (Dividend Reinvestment Plan): By flipping one toggle switch inside your brokerage or IRA account, every cash dividend your funds pay out automatically buys more fractional shares of that exact same fund – which then pay slightly bigger dividends the next quarter without you lifting a finger.
Step 3: The Gen X Runway & The Pillar Strategy
At 50, we sit in a very specific window.
We don't have 35 years to YOLO (see Glossary) our retirement into speculative meme stocks and shrug off an 80% crash. On the flip side, we still have 10 to 15 years before retirement – and hopefully 25+ years in retirement – so stuffing everything under a mattress or into sleepy 2% cash accounts isn't going to cut it either.
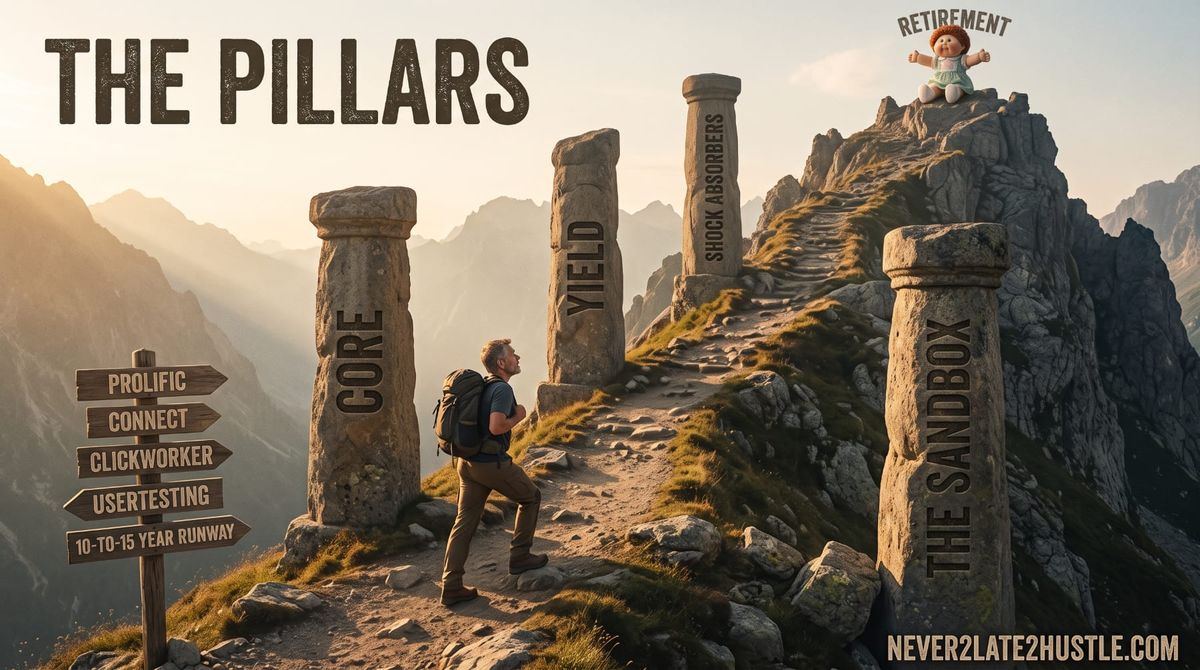
Instead of playing stock-picker, I worked with Gemini and Claude to organize my accounts around some basic pillars. Just like I run different side-hustle platforms so one can pick up the slack when another goes quiet, each pillar in the portfolio has a specific job:
Pillar 1: Core Equity & Growth (The Heavy Lifters)
This is the foundation. Instead of trying to guess which individual company will win the next decade, this pillar uses broad-market index funds and growth ETFs to own a slice of the whole haystack. When the broader economy and corporate earnings grow over a 10-to-15-year window, this pillar does the heavy lifting.
Pillar 2: Dividend Growth & Targeted Yield (The Cash-Flow Snowball)
Confession: I love dividends. Seriously. Like the kids, my wife, the dogs – dividends. There is something deeply motivating – especially when you're grinding out $1.00 surveys – about watching your investments start paying you back in cold, hard cash every month and quarter.
This pillar combines established dividend-growth ETFs (companies that reliably raise their payouts year after year) with targeted income and infrastructure funds. With DRIP turned on, every payout automatically buys more shares, accelerating the compounding flywheel whether the market is up, down, or sideways.
Pillar 3: The Shock Absorbers (Bonds, Managed Futures & Hedges)
When you're 25, a 30% market drop is a buying opportunity. When you're 50+, a multi-year market slump requires a little more respect.
This pillar holds active bond funds, managed futures, and precious metal/commodity hedges – assets designed to zig when the stock market zags, kick off a steady yield, and keep the overall ride smooth enough that I never panic-sell at the bottom.
Pillar 4: The Fenced-Off Sandbox (Scratching the Itch Safely)
Let's be honest: completely giving up the thrill of making an active call or taking a swing at a high-upside idea is hard – that was the whole lesson of Warren Butthead. It is almost daily news how one person made crazy money by buying one dumb thing – that's a lottery and not a plan.But that doesn't mean the lottery dream isn't fun...
Rather than pretending the urge doesn't exist, I built a tiny, strictly quarantined Sandbox representing a very small percentage of the total portfolio. If I want to test a thesis or swing for the fences, it happens inside the Sandbox. If a Sandbox pick strikes out, my retirement math doesn't change – I'm just going to have to wait fifteen years as I planned instead of retiring tomorrow.
Step 4: Know Your Plumbing (IRA vs. Taxable Brokerage)
If there is one technical lesson that saved me the most headaches (documented in The Math Started Mathing), it is understanding where you hold your funds before you hit the buy or sell button:
- Inside an IRA (Individual Retirement Account): You can rebalance, sell a fund you don't like anymore, and reinvest into a better structure without triggering a taxable capital gains event. And when a high-paying fund drops in share price on the day it pays out its annual distribution, DRIP simply scoops up more shares at the lower price tax-free.
- Inside a Taxable Brokerage Account: Every time you sell a winner to move money around, the IRS wants a cut of the gain. In a taxable account, you want to buy things you plan to hold for the long haul so you aren't creating accidental tax bills every time you change your mind.
(Want the plain-English definitions for any of these terms? They are all wired up in The Side-Hustler's Glossary & Lingo.)
The Bottom Line: Why "Boring" Is the Goal
The best part about finally getting these pillars in place is that my investing life is now delightfully boring.
I don't spend my weekends staring at stock charts, reading Wall Street hot takes, or wondering if I should dump everything and buy whatever is trending on Reddit. The structure is already built. Every time a payout lands from Prolific, Connect, Clickworker, or UserTesting, it goes straight across the firewall, buys another handful of fractional shares across the pillars, and lets compounding do the rest.
It's not six million dollars...not yet, anyway.
But fifty cents and ten dollars at a time, we have the technology.
Want to see the exact platform numbers feeding this structure every quarter? Check out The Results, compare the platforms side-by-side in Four Side Hustle Platforms, Compared Honestly, or visit Don't Panic: The Side Hustle FAQ.
How This Post Got Made
The portfolio journey, the hard-earned lessons, and the 5,500+ tasks funding the accounts are all mine. Gemini and Claude helped me stress-test the pillar structure over the past few months, and Gemini helped me shape this evergreen blueprint so I could explain the mechanics without playing stock-picker.
Update Log
- October 2026: Original evergreen blueprint published.